Personal budget: set limits per category in 20 minutes
You do not need a complicated system. A personal budget works when it is specific: not "spend less", but "$350 for groceries this month". Here is how to set it up in about twenty minutes.
Start with what you really spend
Pull your last three months of spending and group it by category. Use the average, not the best month. If you track with an app or a bank export, this takes minutes. If not, your card statements show most of it.
Pick the categories that matter
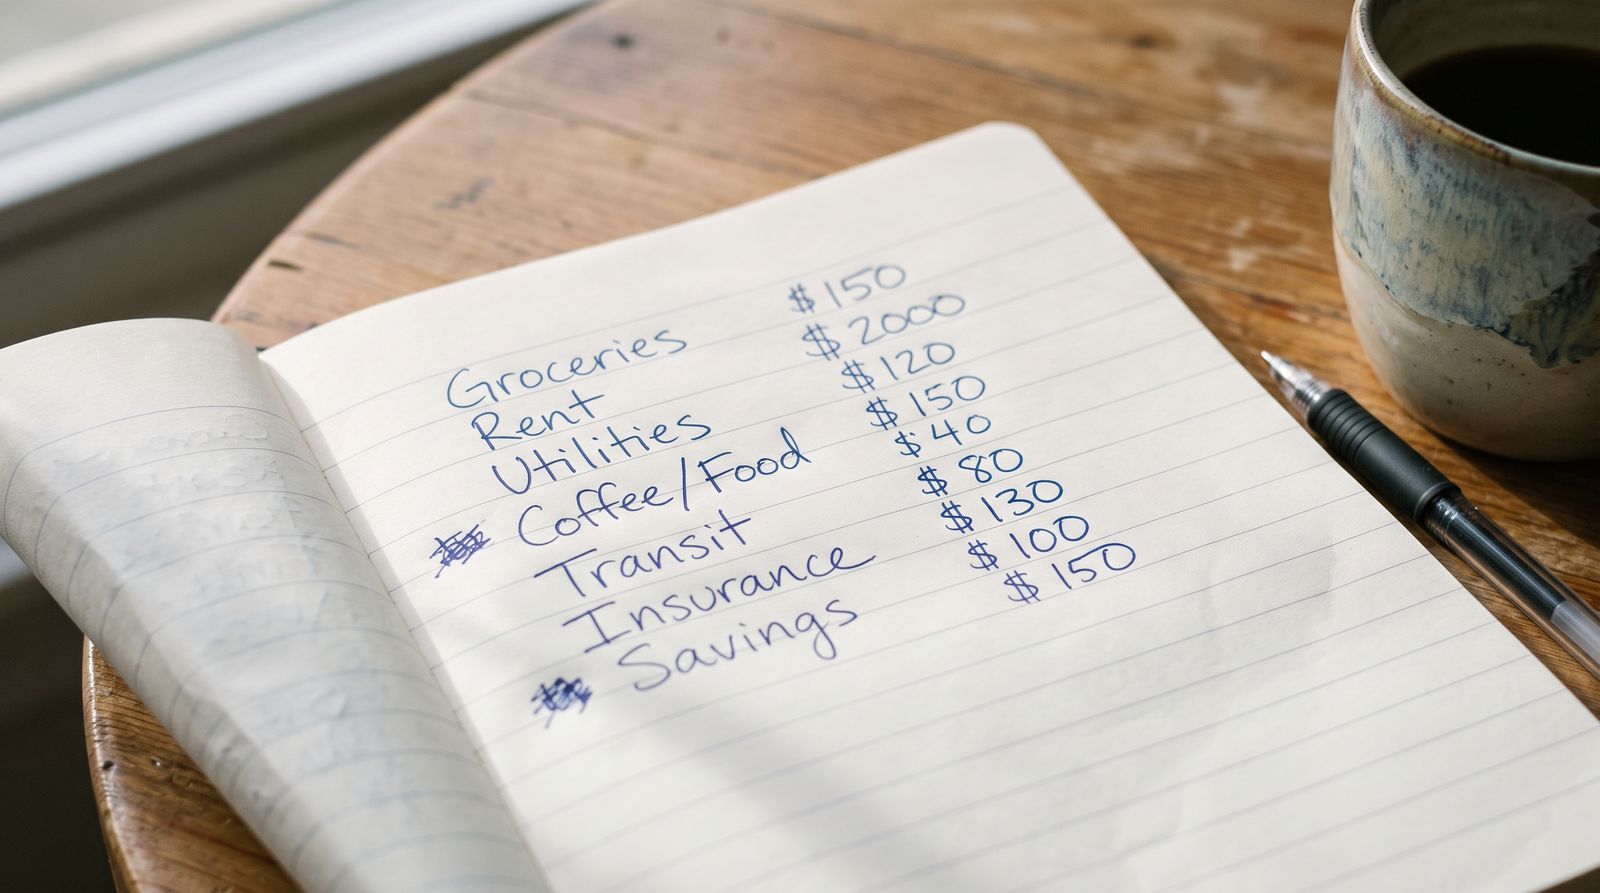
You do not need 25 categories. Choose the handful where money tends to escape: groceries, eating out, transport, shopping, subscriptions. Fixed costs like rent are already predictable.
Set the limit
- Fixed costs: use the exact amount.
- Flexible categories: set the limit about 5% to 10% under your average. Small cuts last longer than big ones.
- Savings: treat it like a bill and pay it first.
Example: if you averaged $420 on groceries and $260 on eating out, set $390 and $230. That frees $60 a month without feeling like a diet.
Check it weekly, not daily
A short weekly look is enough: how much of each limit is used, and how many days are left in the month. If a category is at 50% on day 10, you are on a path to go over. Adjust early.
Handle the months that go wrong
Some months have extra costs: a repair, a trip, a gift. Decide in advance which category gives way, or use a small "surprise" category. The goal is not perfection, it is knowing where the extra went.
Frequently asked questions
How many categories should I budget?
Start with four to six where you tend to overspend. You can add more later.
Should I include irregular costs like car repairs?
Yes, as a monthly amount. Add up what you spent on them in the last year and divide by 12.
What if I overspend one month?
Look at why, adjust the limit if it was unrealistic, and move on. One bad month does not break a budget.
Is this the same as 50/30/20?
No. 50/30/20 splits your income into three big buckets. Category limits are more detailed and can sit inside those buckets.
Sources
Educational information, not financial, tax or legal advice. Rules and tools change: check the sources above for current details.
Kuentaly reads your bank alerts, organizes your cards and shows your registered accounts. Free to use during the beta.
Open Kuentaly